
Back to blog
Article
2022 Office Chair
Admin October 08, 2026
In 2022, the office chair industry exhibited characteristics of industrial clustering, intense competition, and relatively low market concentration.
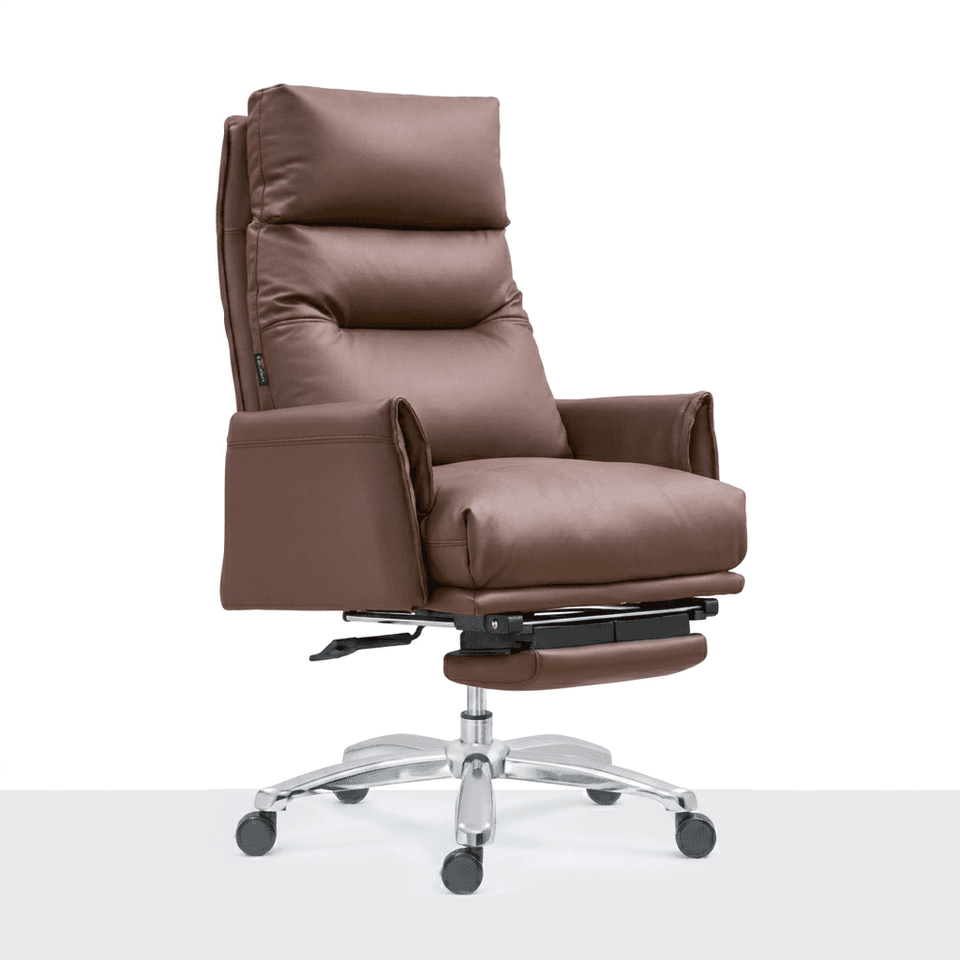
Industry Overview and Classification
Office chairs are chairs equipped for the convenience of work, with a wide variety of types, including executive chairs, manager chairs, reception chairs, staff chairs, conference chairs, visitor chairs, training chairs, etc. They can be classified according to criteria such as material composition, usage type, and usage occasion.
Industrial Chain Structure
- Upstream: It mainly includes industries such as hardware components, sponges, wood, iron frames, leather, and plastics, involving enterprises like Hettich, Dongtai, Kingfa Science and Technology, and Shagang Group. Among them, steel production maintained a growth trend in 2020, with pig iron, steel products, and crude steel production reaching all-time highs. Fabric production showed a declining trend from 2016 to 2020 but generally met downstream demand.
- Midstream: Office chair manufacturers mainly include Yongyi Co., Ltd., Henglin Co., Ltd., Botai Furniture, and Boyi Furniture.
- Downstream: The consumer groups mainly include enterprises and institutions, government agencies, and residential household users, with enterprises and institutions and government agencies being the main ones at the current stage.
Competitive Landscape
- Competitive Tiers: The entry barrier in China's seating industry is relatively low, with a large number of enterprises and a significant proportion of small and medium-sized enterprises. Among them, only Yongyi Co., Ltd. and Henglin Co., Ltd. are listed companies, while non-listed enterprises with certain competitiveness include Boyi Furniture, Botai Furniture, and Lianyou Furniture. The high-end segment is dominated by leading foreign office chair enterprises, followed by some Chinese OEM/ODM enterprises mainly engaged in exports, and the rest are regional enterprises in the low- and mid-end segments. The vast majority of Chinese enterprises are in the low- and mid-end tiers.
- Market Share: In 2020, in terms of revenue scale, Yongyi Co., Ltd. and Henglin Co., Ltd. had market shares of 8.90% and 8.71% respectively; in terms of sales volume scale, their shares were 3.56% and 3.63% respectively.
- Market Concentration: In 2020, the combined total sales of Yongyi and Henglin accounted for 17.61%, and their combined export sales accounted for 13.85%, which were relatively low compared to the US office furniture market. The reasons are that export products are targeted at the low- and mid-end markets in Europe and the United States, with low product differentiation and an unformed brand effect among enterprises.
- Competitive State: There are a large number of enterprises, with a significant number of small, medium, and micro enterprises, a small number of leading enterprises, and an even smaller number of listed companies. Moreover, the industry has serious product homogeneity, intense competition among existing competitors, and weak bargaining power with upstream suppliers.


